
Should Tampa Bay Buyers Wait for Lower Mortgage Rates?

Imagine putting your Tampa Bay home search on hold for a year, only to find mortgage rates barely moved. Frustrating to think about — but it’s a real possibility for buyers who are banking on a big rate drop.
A lot of buyers I talk with across Wesley Chapel, Lutz, Odessa, and New Tampa are pausing their plans because they believe significantly lower rates are just around the corner. Based on the latest forecasts, that may not happen. Before you put your Tampa Bay home search on pause, here’s what the data actually shows — and the options that could help you move forward anyway.
Why Experts Don’t Expect a Big Rate Drop
If you’re holding out for mortgage rates to fall, you’re not alone. A recent survey found that 42% of people expect rates to drop below 5% this year. The problem: that’s not what the experts who track rates for a living are forecasting.
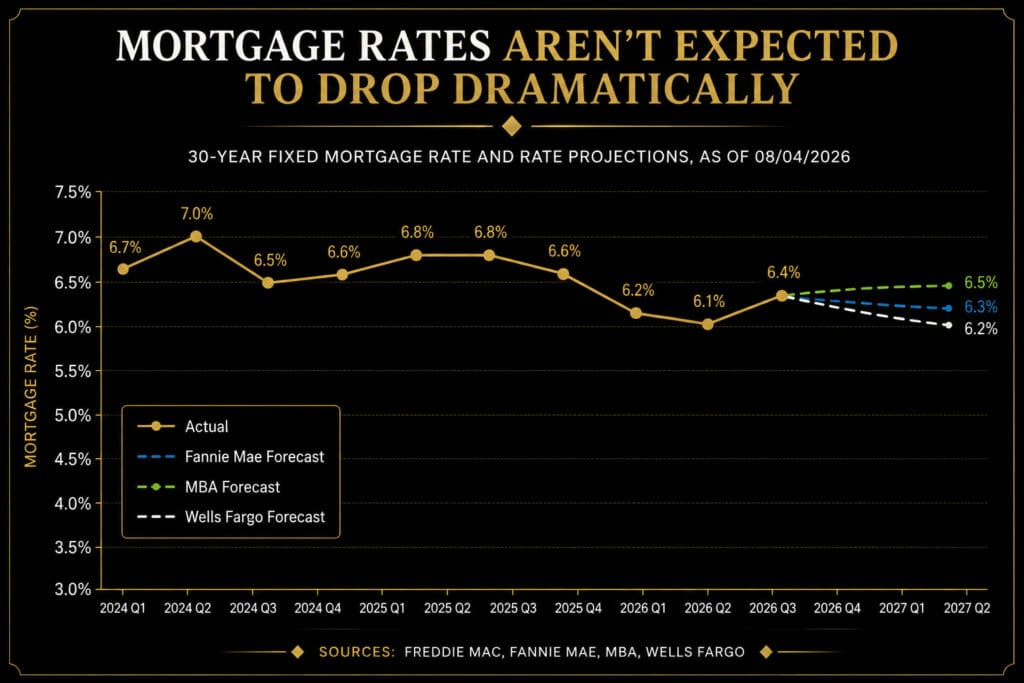
National forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all point to rates holding in the low-to-mid 6% range through at least mid-2027. Rates are shaped by inflation, the broader economy, Treasury yields, Federal Reserve policy, and global events — and right now, those factors aren’t lining up for a dramatic drop.
Could rates shift slightly in either direction? Absolutely. But if you’re waiting on a major decline before searching for homes in Tampa Bay, you may be waiting far longer than expected. That’s a costly bet if home prices or your ideal neighborhood’s inventory shift in the meantime.
Inflation Is Working Against Lower Rates
One of the biggest reasons experts aren’t forecasting a meaningful rate decline comes down to inflation. Generally speaking, elevated inflation and lower mortgage rates don’t move together.
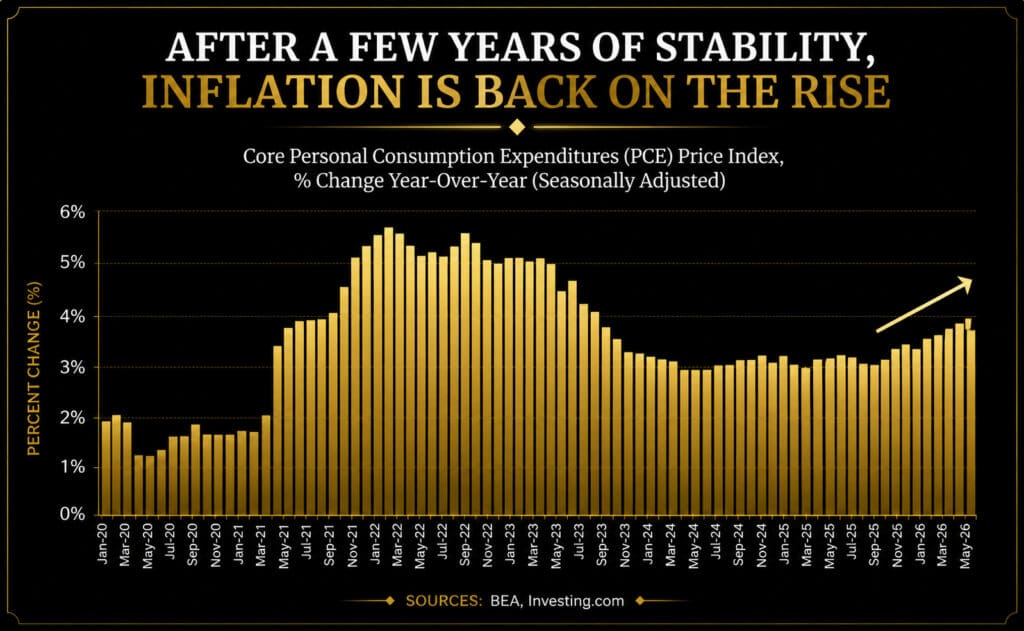
After a period of relative stability, national inflation data has trended higher in recent months. That matters because one of the key ingredients needed for significantly lower mortgage rates simply isn’t in place right now.
For Tampa Bay buyers, this is worth understanding in context. Local home values in submarkets like Wesley Chapel, Land O’ Lakes, and San Antonio are shaped by supply, new construction pipeline, and buyer demand — not national rate forecasts alone. But financing costs still affect monthly affordability regardless of where you’re buying.
This is exactly why I encourage my clients to stop tracking rate headlines in isolation and instead look at their full financial picture: what a given rate means for their actual monthly payment on a specific Tampa Bay home, and whether today’s inventory and pricing outweigh the cost of waiting. A lender partner can model this out precisely for your situation.
Today’s Rates Aren’t High — They’re “Normal”
Here’s a mindset shift worth sitting with: while today’s rates feel high compared to a few years ago, historically speaking, they’re not. They’re within a normal, expected range.
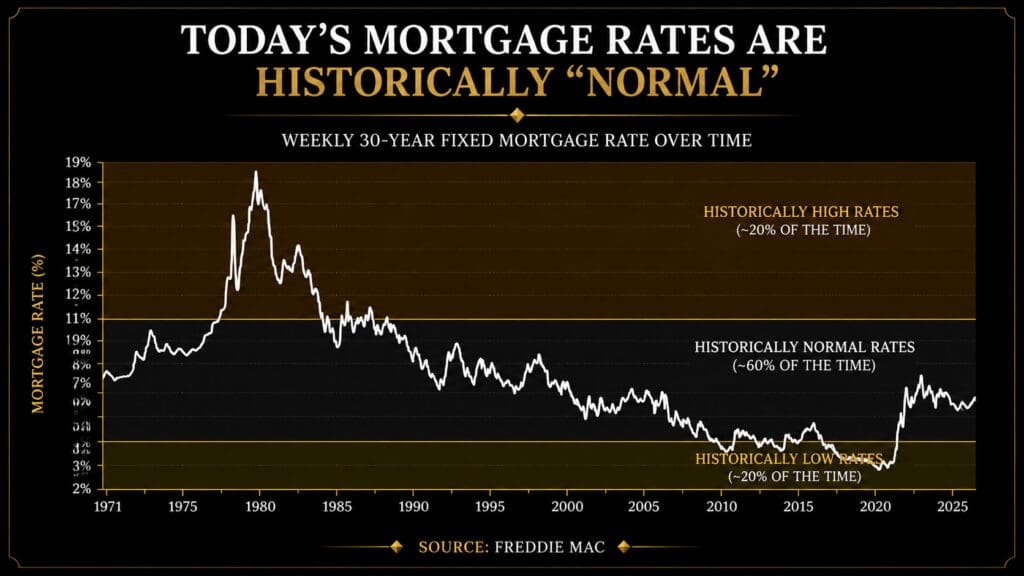
Mortgage rates have historically spent most of their time somewhere between roughly 5% and 10%. National data from Freddie Mac shows current rates falling well within that long-term range. It feels high mainly because many buyers remember the unusually low rates available during the pandemic — a period that was the exception, not the norm.
This doesn’t mean a 6%-range mortgage suddenly feels exciting. But it’s a helpful reminder that waiting indefinitely for pandemic-era rates to return isn’t a realistic strategy for most Tampa Bay buyers.
What matters more for your bottom line is your specific loan terms, your down payment strategy, and the price you’re able to negotiate on a home — all things a knowledgeable local agent can help you navigate regardless of where national rates sit.
What Tampa Bay Buyers Can Do Instead of Waiting
None of this means you have to buy today. But if your plans have changed — a growing family, a job relocation, a lease ending — there are ways to improve affordability without waiting on rates to fall.
Explore new construction incentives. Builders across Wesley Chapel, Land O’ Lakes, and San Antonio are actively offering price adjustments, closing cost credits, and rate incentives to move inventory.
Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay long-term, an ARM may offer a lower initial rate than a fixed 30-year loan. It isn’t right for everyone, but it’s worth discussing with a lender.
Look into mortgage rate buydowns. Paying upfront to reduce your rate can lower your monthly payment without waiting on the market to shift.
Ask about assumable mortgages. In select cases, buyers can take over a seller’s existing loan — lower rate included.
The takeaway: waiting isn’t your only option. A conversation with your Realtor and lender can uncover strategies suited to your specific goals.
Investment Perspective
For investors and move-up buyers, waiting on rates carries its own risk: home prices and rents in growing Pasco and Hillsborough County submarkets have historically continued moving over time, meaning the “wait for a better rate” strategy can be offset by a higher purchase price later.
Buyers using ARM products, buydowns, or builder-negotiated incentives today can often refinance later if rates do eventually ease — locking in today’s home price while keeping financing flexible. This strategy is worth modeling with your lender against your specific investment timeline and goals rather than assuming any single national forecast will play out exactly as projected.
Future Outlook
Current forecasts point to rates holding in a fairly steady range into 2027, though unexpected economic shifts could move that timeline in either direction. For Tampa Bay’s Pasco and Hillsborough County growth corridors specifically, continued population growth, new construction pipeline, and relocation demand remain the more consistent forces shaping local home values and inventory — independent of where national rates ultimately land.
Explore Homes in Tampa Bay
Don’t Let a Rate Forecast Cost You the Right Home
While you’re weighing whether to wait on rates, Tampa Bay’s most sought-after communities aren’t waiting on you. Builder incentives, rate buydown programs, and motivated sellers are available right now across Pasco and Hillsborough County — and the homes offering the strongest incentives tend to move quickly.
Browse homes currently offering builder incentives, rate buydowns, or seller concessions:
• New Tampa
• Riverview
• Apollo Beach
• Land O’ Lakes
• San Antonio
👉 Want a Custom Rate + Affordability Breakdown for a Specific Home?
Elena Esquen, MBA
Realtor® & Broker Associate
New Construction Specialist & Relocation Expert
Coldwell Banker Realty
📱 Phone: 813-822-4261
✉️ Email: Homes@EsquenTampaBay.com
🌐 Website: EsquenTampaBay.com
🏠 Resources: TampaHomesToday.com
🌴 Serving the Greater Tampa Bay Area
Frequently Asked Questions
1. Are mortgage rates expected to drop below 5% soon?
Most major forecasters — including Fannie Mae, the Mortgage Bankers Association, and Wells Fargo — project rates holding in the low-to-mid 6% range through at least mid-2027, not dropping below 5%.
2. Why aren’t mortgage rates falling right now?
Inflation remains elevated, and rates are also influenced by Treasury yields, Federal Reserve policy, and broader economic conditions — none of which currently point toward a significant rate decline.
3. Are today’s mortgage rates actually high?
Historically, mortgage rates have spent most of their time between roughly 5% and 10%. Today’s rates fall within that normal historical range; they only feel high compared to the unusually low pandemic-era rates.
4. Should I wait to buy a home in Tampa Bay until rates drop?
That depends on your personal timeline and goals. If your plans haven’t changed, waiting may make sense. If your life circumstances require a move, strategies like ARMs, buydowns, and builder incentives can help now.
5. What is a mortgage rate buydown?
A rate buydown is when a buyer or seller pays an upfront cost to reduce the buyer’s interest rate, lowering the monthly payment without needing rates to fall on their own.
6. Are new construction homes in Wesley Chapel offering incentives right now?
Many builders across Wesley Chapel, Land O’ Lakes, and San Antonio are currently offering price adjustments, closing cost credits, or rate incentives — Elena can provide an updated list of active builder promotions.
7. What is an assumable mortgage?
An assumable mortgage allows a qualified buyer to take over the seller’s existing loan, including its original interest rate, which can sometimes be lower than current market rates.
8. How can Elena Esquen help me navigate mortgage rate uncertainty?
Elena connects buyers with trusted local lenders to model real numbers for specific homes and neighborhoods, helping clients make confident decisions instead of guessing based on national rate headlines.
Disclaimer
This article is intended for informational purposes only and should not be considered financial, legal, tax, or real estate advice. Mortgage rate forecasts referenced above (Fannie Mae, Mortgage Bankers Association, Wells Fargo, Freddie Mac) reflect national data and projections, not Tampa Bay-specific figures, and market conditions can change at any time. For personalized guidance regarding your real estate and financing goals in Tampa Bay, Wesley Chapel, Lutz, Odessa, San Antonio, or surrounding Florida communities, contact Elena Esquen directly.
Elena Esquen, REALTOR®, Coldwell Banker Realty, is an Equal Housing Opportunity provider. This content does not constitute financial or lending advice; consult a licensed mortgage professional for guidance specific to your situation.