
Tampa Bay Mortgage Rates: The Headline Number Isn’t Your Number
If recent headlines about rising mortgage rates have you second-guessing a move, pause before you change your plans. The rate you see in the news or on social media is a broad average, not a personal offer. Tampa Bay mortgage rates vary from buyer to buyer, and the rate you qualify for could be higher or lower than what you’re reading online.
For buyers relocating to Wesley Chapel, Riverview, Lutz, Land O’ Lakes, and nearby communities, knowing this difference can decide whether now is the right time to buy.
What Actually Determines Your Mortgage Rate
Advertised rates are based on assumptions about a “typical” borrower. Your real rate is based on you. A lender will review several factors to calculate it:
- Credit score: Lenders weigh your payment history, how much of your available credit you use, and how long your accounts have been open. Stronger credit generally earns a lower rate.
- Debt-to-income ratio (DTI): Your monthly debt payments divided by your gross monthly income. A lower DTI signals less risk and can improve your rate.
- Down payment and loan-to-value (LTV): The more you put down, the smaller the share of the home’s price you borrow, which can work in your favor.
- Loan type and term: Conventional, FHA, VA, and USDA loans, plus 15- and 30-year terms, are each priced differently. Your loan officer will show you which programs you qualify for.
Because each factor is personal, no headline can predict your number. Only a lender reviewing your finances can.
How Incentives Can Lower Your Rate in Tampa Bay
Your rate can still improve after you find the right home.
- Mortgage rate buydowns: Paying an upfront fee to reduce your interest rate, either temporarily or for the life of the loan, lowers your monthly payment. In Tampa Bay’s new construction market, builders often offer to cover buydown costs as an incentive, particularly in growing communities like Wesley Chapel, Land O’ Lakes, and Riverview.
- Seller concessions: Most loan programs allow sellers to contribute toward a buyer’s closing costs. Those savings can reach thousands of dollars, freeing up cash for a larger down payment, paying down debt, or buying down your rate.
Knowing which incentives are available, and how to negotiate them, is where an experienced local agent makes a measurable difference.
Your First Step: Get Pre-Approved
To learn whether your rate lands above or below the headlines, talk with a trusted loan officer. One conversation can show you how much you can borrow, when you’ll be ready to buy, and what your rate could be.
Your lender may mention two options:
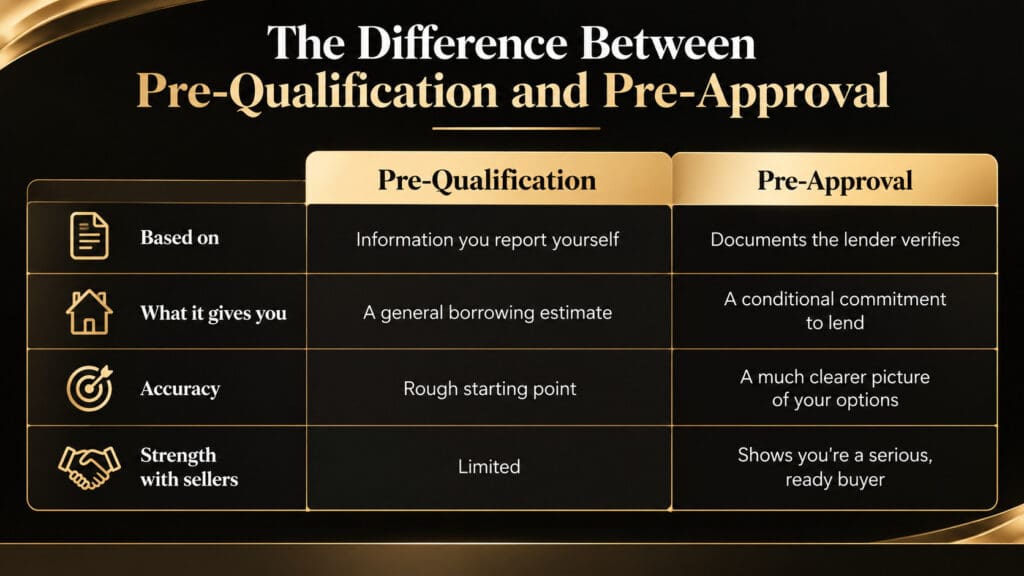
Pre-approval gives you the more accurate view of your real rate and buying power. It also makes your offer more competitive when the right home comes along.
Questions to Bring to Your Lender
Before your appointment, ask your lender which documents to gather, such as pay stubs, tax returns, and bank statements. Then bring these questions:
- What would I gain or lose by waiting 3, 6, or 12 months to buy?
- Are there tax advantages to owning a home, and what are they?
- How does building equity now compare with waiting, and how does that affect my long-term finances?
- How would rate changes, up or down, affect my payment and budget?
Once you know your real rate, you may find you’re ready to buy now, or you may decide a short wait makes sense. Either way, you’ll be deciding based on your own numbers.
Bottom Line
Headlines can make today’s mortgage rates sound out of reach, but the rate you see online may not be the rate you get. The only way to know is to speak with a trusted lender and a local expert who understands the Tampa Bay market.
Let’s find out what your real rate is and where it can take you.
Explore Homes in Tampa Bay
Elena Esquen, MBA
Realtor® & Broker Associate
New Construction Specialist & Relocation Expert
Coldwell Banker Realty
📱 Phone: 813-822-4261
✉️ Email: Homes@EsquenTampaBay.com
🌐 Website: EsquenTampaBay.com
🏠 Resources: TampaHomesToday.com
🌴 Serving the Greater Tampa Bay Area
Frequently Asked Questions
1. Why is my mortgage rate different from the rate I see online?
Online and headline rates are averages based on a typical borrower. Your rate depends on your credit score, debt-to-income ratio, down payment, and loan type, so it can be higher or lower than what’s advertised.
2. How can I get a lower mortgage rate in Tampa Bay?
Improving your credit, lowering your debt, and making a larger down payment can all help. In Tampa Bay’s new construction market, builder incentives such as rate buydowns or closing cost contributions can also reduce your rate or monthly payment.
3. What is a mortgage rate buydown?
A buydown is an upfront payment that lowers your interest rate, either for the first few years or for the life of the loan. A builder, seller, or other party may pay this cost for you as an incentive.
4. What’s the difference between pre-qualification and pre-approval?
Pre-qualification is an estimate based on information you provide. Pre-approval is a conditional commitment from a lender based on verified documents, so it gives you a more accurate picture of your rate and budget.
5. Does getting pre-approved affect my credit score?
A pre-approval usually involves a hard credit inquiry, which may cause a small, temporary dip. Rate-shopping with several lenders within a short window is typically treated as a single inquiry. Ask your lender how they handle it.
6. Should I wait for rates to drop before buying?
It depends on your finances and goals. Waiting could mean higher home prices or missed builder incentives, while buying now lets you start building equity. A lender can compare both scenarios using your actual numbers.
7. Can I use seller concessions to lower my rate?
Yes. Most loan programs allow sellers to contribute toward closing costs, and those funds can often be applied to a rate buydown. Contribution limits vary by loan type.
Disclaimer
This article is for general informational purposes only and does not constitute financial, lending, tax, or legal advice. Elena Esquen and Coldwell Banker Realty are not mortgage lenders. Mortgage rates, loan programs, and eligibility requirements vary by lender and borrower and are subject to change without notice. Consult a licensed loan officer for rate quotes and loan qualification, and a qualified tax professional regarding potential tax benefits of homeownership.
Builder incentives, rate buydowns, seller concessions, pricing, and property details in any featured listing are subject to change, availability, and qualification, and should be verified directly with the builder or listing agent. Information is deemed reliable but not guaranteed.
Equal Housing Opportunity.