
Buying a Home in Tampa Bay? Here’s What You Should Know About Insurance Costs

If you’re house hunting, you’re probably watching mortgage rates and listing prices closely. But there’s a third number that deserves just as much attention: homeowners insurance.
For Tampa Bay buyers especially, insurance isn’t a footnote. It’s a real part of your monthly budget, and it can vary block by block depending on flood zone, roof age, and construction type. Here’s what to know before you write an offer.
Insurance Costs Have Been Rising Nationally
Before diving into the numbers, it helps to define the term. A “luxury home” typically refers to properties in the top 5% of price range for a given area — meaning the exact price threshold varies from Wesley Chapel to South Tampa to Odessa.
According to recent data from Redfin, luxury home prices have been climbing nearly three times faster than prices for non-luxury homes. The typical home nationally is up around 1.5% year-over-year, while high-end homes have risen closer to 5% over the same period.
For Tampa Bay’s luxury sellers, that’s a meaningful signal. Despite widespread talk of slowing price growth, the upper end of the market appears to be moving at a noticeably faster pace — a trend worth understanding before you decide when to list your Wesley Chapel, Lutz, or Odessa luxury property.
Florida’s Insurance Landscape Is Unique
Florida homeowners insurance tends to rank among the more expensive in the country, largely due to hurricane and severe storm exposure. That reputation is well-earned, but it’s also becoming a more manageable picture than it was a few years ago.
Recent state-level reforms have helped stabilize the market and slow the pace of increases. Several private insurers have also re-entered Florida, giving buyers more competition and choice than during the tightest years of the market.
For Tampa Bay buyers specifically, a few local factors matter most:
- Flood zone status – A home’s FEMA flood designation can significantly affect whether flood insurance is required and what it costs.
- Wind mitigation features – Newer roofs, impact windows, and hurricane straps often qualify for meaningful discounts.
- Construction age and type – Block construction and updated electrical or plumbing systems typically insure more favorably than older frame homes.
Always verify flood zone and insurance details directly with a licensed insurance professional for your specific address.
Premiums Are Rising, But the Pace Is Slowing
Here’s the part that gets less attention: while premiums are still going up, the rate of increase has started to ease. Industry data shows 2025 marked the first meaningful slowdown in annual premium growth in several years.
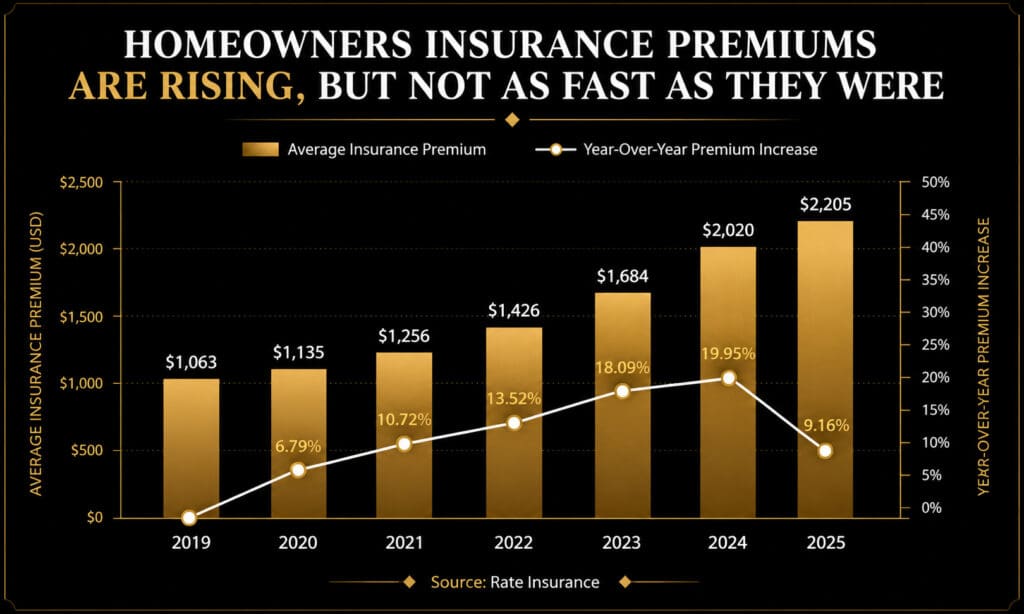
That doesn’t mean insurance is getting cheaper. It means the sharpest jumps of the past few years may be behind us, at least for now.
For Tampa Bay buyers, this is genuinely useful news. Many communities across Wesley Chapel, Lutz, Odessa, Land O’ Lakes, and New Tampa feature newer construction, which often insures more favorably than older housing stock elsewhere in the state. Builder-grade roofs, modern wind mitigation features, and updated codes can translate into real savings.
Every policy is different, so the best move is always to request quotes tailored to the specific home and address you’re considering, rather than relying on statewide averages alone.
Where You Buy Can Make a Real Difference
Insurance costs aren’t uniform, even within Tampa Bay. Your premium depends on the specific home, its distance from water, its age and construction, and the coverage level you choose.
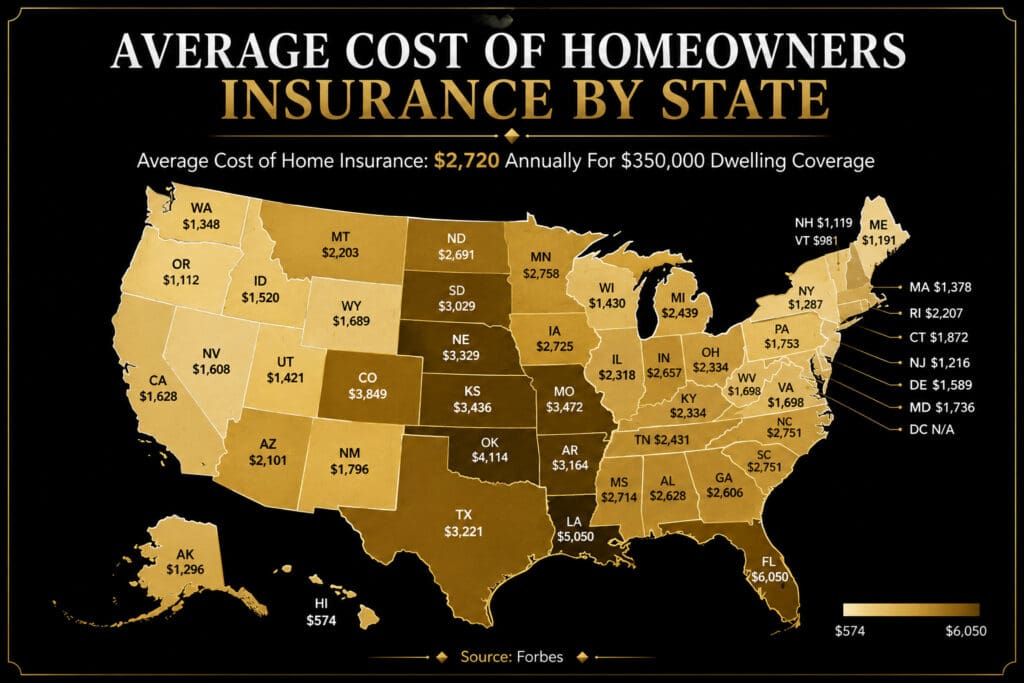
This is where local guidance matters most. A home in a coastal-adjacent Hillsborough neighborhood may carry different flood insurance requirements than a comparable home in inland Pasco County. Utility infrastructure, elevation, and community-specific factors (like CDD assessments in many master-planned communities) all play a role in your true monthly cost.
Before writing an offer, it’s worth asking:
- Is this home in a mapped flood zone?
- Does the community carry CDD fees in addition to HOA dues?
- What year was the roof installed, and does it qualify for wind mitigation credits?
These questions matter just as much as square footage and school zones when you’re comparing homes across Tampa Bay submarkets.
Ways to Lower Your Insurance Costs
You can’t control the insurance market, but you can control how prepared you are. A few proven ways to reduce your premium:
- Shop around – Compare quotes from multiple carriers rather than accepting the first one.
- Bundle policies – Combining home and auto coverage often unlocks a lower combined rate.
- Ask about discounts – Many carriers offer credits you have to specifically request.
- Highlight upgrades – A newer roof, impact windows, or hurricane shutters can meaningfully lower cost.
- Improve your credit – A stronger credit profile can translate into better premium offers.
One of the smartest moves a Tampa Bay buyer can make is requesting an insurance quote before submitting an offer. That way, your true monthly housing cost is clear before you’re under contract, not after.
A trusted local insurance professional can walk you through coverage options that fit both your budget and your new address.
Explore Homes in Tampa Bay
Explore More Homes Throughout Tampa Bay
Not finding the perfect home in your preferred neighborhood? Expanding your search can open the door to more opportunities, better value, and additional inventory throughout the Tampa Bay area.
Browse Homes for Sale In:
• New Tampa
• Riverview
• Apollo Beach
• Land O’ Lakes
• San Antonio
Whether you’re looking for new construction, waterfront living, luxury homes, family-friendly communities, or more affordable options, these growing Tampa Bay neighborhoods offer something for every lifestyle and budget.
Need a customized home search? I can help you compare communities, identify the best opportunities, and find the right home based on your goals.
👉 Start your personalized home search today.
Elena Esquen, MBA
Realtor® & Broker Associate
New Construction Specialist & Relocation Expert
Coldwell Banker Realty
📱 Phone: 813-822-4261
✉️ Email: Homes@EsquenTampaBay.com
🌐 Website: EsquenTampaBay.com
🏠 Resources: TampaHomesToday.com
🌴 Serving the Greater Tampa Bay Area
Frequently Asked Questions
1. Is homeowners insurance included in my mortgage payment in Tampa Bay?
Yes, in most cases. Lenders typically require insurance to be escrowed, meaning it’s collected monthly along with your mortgage principal, interest, and property taxes.
2. Why is Florida homeowners insurance more expensive than other states?
Florida’s hurricane and severe weather exposure, along with historically higher rebuilding costs, are the primary drivers behind the state’s higher average premiums.
3. Are insurance premiums still rising in Tampa Bay?
Premiums are still increasing, but recent data shows the pace of those increases has started to slow compared to the previous several years.
4. What is a flood zone, and does it affect every Tampa Bay home?
Not every home requires flood insurance. It depends on the property’s FEMA flood zone designation, which should always be verified for the specific address.
5. Does a new roof lower my insurance premium?
Often, yes. Newer roofs and other wind mitigation features frequently qualify homeowners for meaningful insurance discounts in Florida.
6. Should I get an insurance quote before making an offer?
It’s highly recommended. An early quote helps you understand your true monthly housing cost before you’re under contract.
7. Do new construction homes in Wesley Chapel or Land O’ Lakes insure more affordably than resale homes?
Often yes, since newer homes typically meet updated building codes and wind mitigation standards that many carriers reward with lower rates.
8. How can Elena Esquen help me navigate insurance costs while home shopping?
Elena helps buyers factor insurance, flood zone status, and CDD or HOA costs into their search from day one, so there are no surprises after closing.
Disclaimer
This article is intended for informational purposes only and should not be considered financial, legal, tax, or insurance advice. Insurance premiums, coverage requirements, and flood zone designations vary by property and can change at any time. For personalized guidance on insurance costs and buying a home in Tampa Bay, Wesley Chapel, Lutz, Odessa, San Antonio, or surrounding Florida communities, contact Elena Esquen directly, and consult a licensed insurance professional for a quote specific to your address.
This content complies with the Fair Housing Act. No demographic profiling or steering is intended or implied.