
The Mortgage Rate in the Headlines Isn’t Necessarily Yours
Headlines about rising Tampa Bay mortgage rates can make any buyer pause. Maybe you saw a rate on the news and decided to wait. However, that number may not be the rate you would actually receive.
Here’s the truth. Published rates are averages built for headlines, not for your finances. Your real rate depends on your credit, your debt, your down payment, and the loan you choose. In addition, incentives from sellers and builders can change the math.
I see this every week. Buyers across Wesley Chapel, Lutz, Odessa, and New Tampa often discover their numbers look different than they expected. Others learn exactly what to improve before they buy. Either way, they make decisions with facts instead of fear.
In this guide, I’ll walk you through what really determines your mortgage rate and how to find yours.
Why Headline Tampa Bay Mortgage Rates Aren’t Your Rate
Most rates you see online are national averages. Many national surveys, such as Freddie Mac’s weekly survey, reflect borrowers with strong credit and about 20% down. As a result, they’re useful benchmarks, but they aren’t quotes.
Rates also move constantly, sometimes from one day to the next. Therefore, last week’s headline may already be outdated.
Most importantly, an average can’t account for you. It doesn’t know your credit history, your income, or the home you want. Only a lender can review those details and give you an accurate figure.
Here’s what that means locally. Buyers relocating to Tampa Bay from higher-cost markets sometimes arrive with substantial equity from a home sale. Their real rate could differ noticeably from the headline. On the other hand, some first-time buyers find that a few small changes improve their numbers before they apply.
What Lenders Review to Set Your Real Rate
Every lender looks at a few core factors. Understanding them puts you in control.
Your Credit Score
Lenders review your payment history, how much available credit you use, and how long your accounts have been open. Generally, a higher score can qualify you for a better rate.
Your Debt-to-Income Ratio (DTI)
This compares your monthly debt payments with your gross monthly income. A lower DTI signals less risk, which can help your rate.
Your Down Payment and Loan-to-Value (LTV)
Your down payment is the share of the price you pay upfront. LTV is the share you borrow. Typically, a larger down payment lowers your LTV and may improve your pricing.
Your Loan Type and Term
Conventional, FHA, VA, and other programs each price differently. Likewise, a 15-year loan and a 30-year loan rarely carry the same rate. Your loan officer will explain which options fit your goals.
How Builder Incentives and Seller Concessions Can Lower Your Payment
Your finances aren’t the only factor. The home and the deal can affect your rate too.
A mortgage rate buydown lets you pay an upfront fee in exchange for a lower interest rate. As a result, your monthly payment drops. Some buydowns are temporary, while others last the life of the loan. Sometimes a builder or seller covers that cost as an incentive.
This is especially relevant in new construction communities across Wesley Chapel, Land O’ Lakes, San Antonio, and Zephyrhills. Builders often advertise incentives, and some are tied to using a preferred lender. However, terms vary by builder, community, and timing, so every offer deserves a careful review.
Seller concessions work differently. Most loan programs allow sellers to pay part of a buyer’s closing costs, within set limits. That freed-up cash could go toward a larger down payment or paying down debt.
As a Certified Negotiation Expert (CNE), I help clients compare incentives side by side. That way, you’ll know which offer truly saves you the most.
Pre-Qualification vs. Pre-Approval: Know the Difference
Your first real step is a conversation with a loan officer. They’ll help you understand how much you can borrow, when you might be ready, and what rate you could expect.
Along the way, you’ll likely hear two terms:
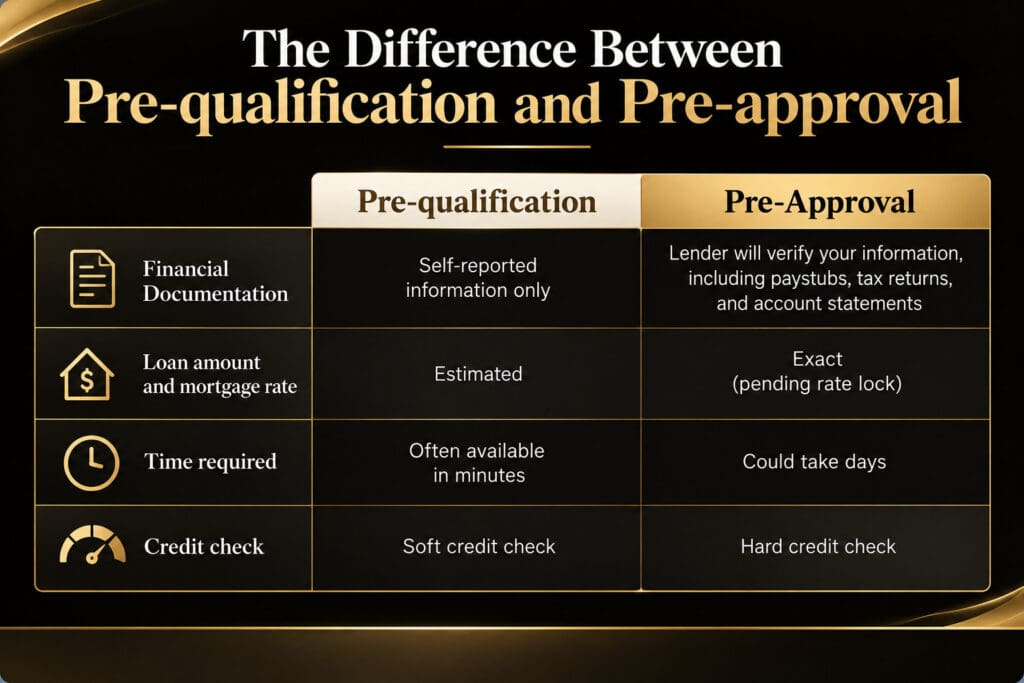
- Pre-qualification: A quick estimate based on information you report yourself. It’s helpful for early planning.
- Pre-approval: A conditional commitment based on verified documents, such as pay stubs, tax returns, and bank statements.
Of the two, pre-approval gives you a far clearer picture. It also carries more weight with sellers. When a home draws interest from multiple buyers, a pre-approval letter shows you’re serious and prepared.
For relocation buyers, this step is especially valuable. You can get pre-approved before you ever fly in for showings. Consequently, your home tour becomes focused and productive instead of exploratory.
Seller Tips: Use Financing to Attract Buyers
Sellers benefit from understanding rates too. Today’s buyers watch their monthly payment closely. So offering help with closing costs or a rate buydown can make your listing stand out.
Consider these strategies:
- Price strategically from day one, based on recent local comparables.
- Discuss concessions early with your agent, rather than waiting for offers to stall.
- Compare the cost of a buydown with the cost of a price reduction.
- Market the monthly payment, not just the price, when incentives are available.
In some cases, a targeted concession may help buyers more than a price cut of similar size. My listing strategy also includes buyers-in-waiting outreach and marketing to the 45,000+ member Moving To Tampa community. Together, these help your home reach motivated, qualified buyers.
The Bottom Line
Headlines can make Tampa Bay mortgage rates sound out of reach. But the rate on the news isn’t the rate on your loan. Your real number depends on your finances, your loan choice, and the incentives available to you.
The only way to know is to talk with a trusted lender and get pre-approved. Then, partner with a local expert who can match that number to the right home.
That’s where I come in. I’ll connect you with reputable lenders, review builder and seller incentives, and help you find a home that fits your goals and budget.
Explore More Homes in Tampa Bay
Elena Esquen, MBA
Realtor® & Broker Associate
New Construction Specialist & Relocation Expert
Coldwell Banker Realty
📱 Phone: 813-822-4261
✉️ Email: Homes@EsquenTampaBay.com
🌐 Website: EsquenTampaBay.com
🏠 Resources: TampaHomesToday.com
🌴 Serving the Greater Tampa Bay Area
Frequently Asked Questions
1. Why is my mortgage rate different from the rates I see online?
Online rates are national averages based on typical borrower profiles. Your actual rate depends on your credit score, debt-to-income ratio, down payment, loan type, and any incentives applied to your purchase.
2.What credit score do I need for a good mortgage rate in Tampa Bay?
Minimums vary by loan program, and higher scores generally earn better pricing. A local lender can review your credit and explain how small improvements might lower your rate.
3. Do builders in Wesley Chapel offer mortgage rate buydowns?Do builders in Wesley Chapel offer mortgage rate buydowns?
Many builders across Wesley Chapel and Pasco County advertise incentives, which may include rate buydowns or closing cost help. Terms vary by builder and change often, so have your agent review each offer.
4. What is the difference between pre-qualification and pre-approval?
Pre-qualification is an estimate based on self-reported information. Pre-approval is a conditional commitment based on verified documents, and it gives you a more accurate picture of your options.
5. Can a seller pay my closing costs in Florida?
Yes. Most loan programs allow seller concessions toward a buyer’s closing costs, within limits set by the loan program. Your agent can negotiate these as part of your offer.
6. Should I wait for mortgage rates to drop before buying in Tampa Bay?
No one can reliably predict rates. Ask your lender what you’d gain or lose by waiting 3, 6, or 12 months, then decide based on your finances and goals.
7. How can I get pre-approved if I’m relocating to Tampa Bay from another state?
You can complete the pre-approval process remotely by submitting documents to a lender. Getting pre-approved before your visit makes home tours far more focused and productive.
Disclaimer
This article is intended for informational purposes only and should not be considered financial, legal, tax, or real estate advice. Market conditions can change at any time. For personalized guidance regarding your real estate goals in Tampa Bay, Wesley Chapel, Lutz, Odessa, San Antonio, or surrounding Florida communities, contact Elena Esquen directly.
Mortgage rate references reflect national-level data and are not specific to Tampa Bay. Elena Esquen is not a mortgage lender. Rates, loan programs, builder incentives, and seller concessions are subject to change and lender approval. Consult a licensed loan officer for current rates and qualification details. Equal Housing Opportunity.