
Should You Use Your 401(k) to Buy a Home in Tampa Bay?
If you’ve seen headlines suggesting your 401(k) could solve your down payment problem, you’re not alone in wondering about it. With affordability stretched thin across much of the country, the idea of using money you’ve already saved can feel like a shortcut worth considering.
As a Tampa Bay REALTOR® who works with buyers relocating from higher-cost markets every day, I hear this question often — especially from families moving to communities like Wesley Chapel, Land O’ Lakes, and New Tampa who are watching their savings closely. Before you make any decision involving your retirement account, it’s worth understanding exactly what’s at stake, what the national data actually shows, and what smarter alternatives might get you into a home here in Tampa Bay without the long-term cost.
Let’s walk through what you need to know.
The Appeal — and the Real Risk — of Tapping Your 401(k)
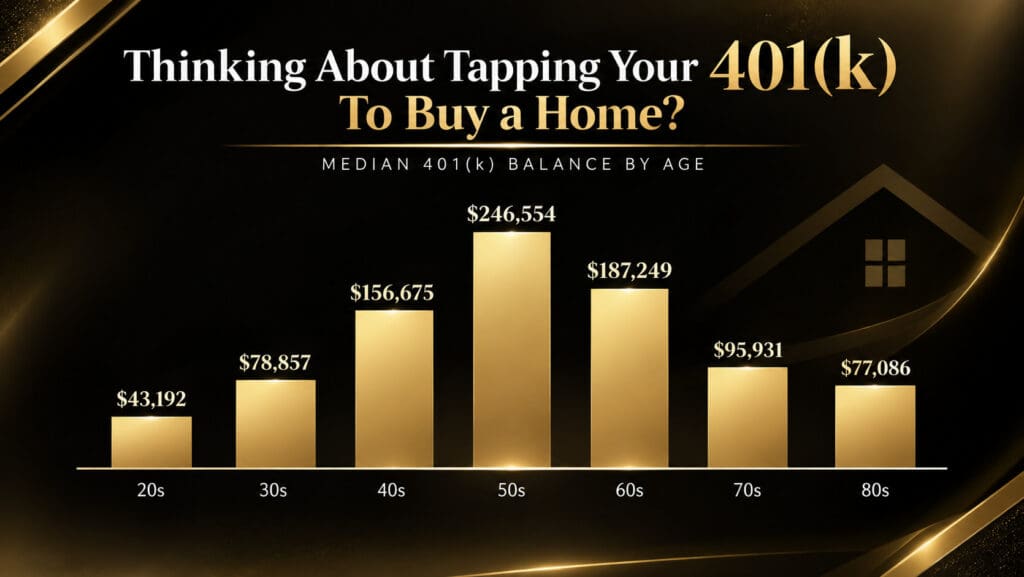
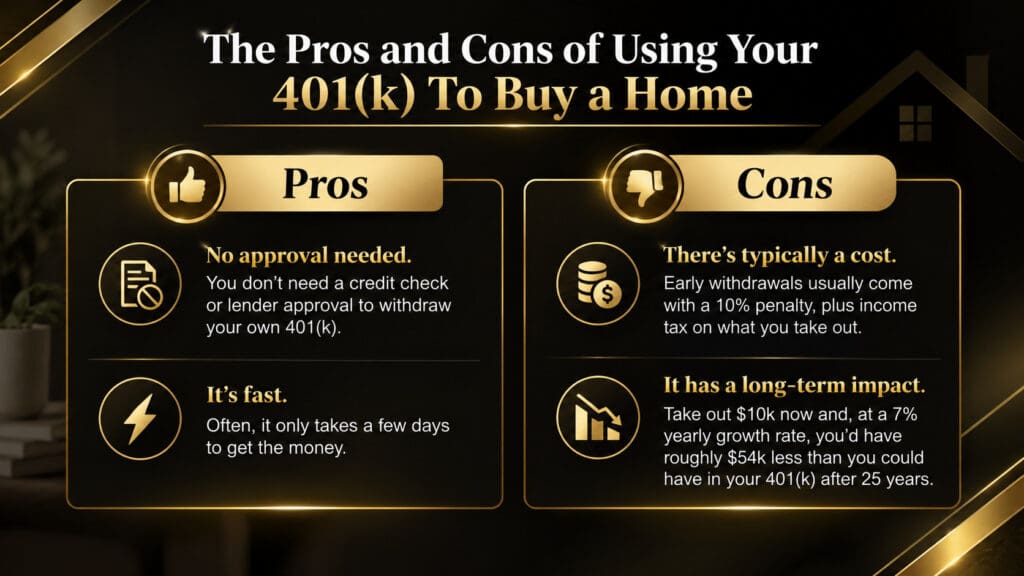
According to national data from Empower, many Americans in their 40s through 60s have built six-figure 401(k) balances. When a buyer sees that number sitting next to a dream home price, borrowing against it can feel like an easy call — especially with today’s affordability pressures making every dollar count.
But national housing analysts caution against moving too quickly. Redfin has noted that while tapping a 401(k) is possible, it carries real risks, including early withdrawal penalties and the loss of future investment growth you can’t easily recover. Bankrate’s comparison of the upsides and downsides echoes this: what looks like fast access to cash today can mean a meaningfully smaller retirement balance decades from now.
This is national commentary, not a Tampa Bay–specific recommendation — but it applies directly here. Buyers relocating to Tampa Bay from higher-cost states often have strong 401(k) balances precisely because they’ve been diligent savers. That discipline is worth protecting, which is why I always encourage a conversation with a financial advisor before any withdrawal decision.
Smarter Down Payment Options Worth Exploring First
Before touching retirement savings, it’s worth exploring financing paths built specifically for today’s buyers. Redfin highlights two worth considering:
- Low and No-Down-Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5%, depending on credit profile.
- Down Payment Assistance Programs: National and local programs exist to reduce what buyers pay toward a down payment or closing costs.
In Tampa Bay specifically, I regularly help buyers navigate builder incentives and preferred-lender programs in master-planned communities throughout Wesley Chapel, Land O’ Lakes, and Odessa — many of which include rate buydowns or closing cost credits that can meaningfully reduce upfront cash needed. First-time buyers relocating from out of state are often surprised at how much further their down payment goes here compared to their home market.
The right combination of loan program, lender relationship, and local incentive knowledge can often close the affordability gap without ever touching a retirement account.
What This Means for Buyers Relocating to Tampa Bay
For families relocating to Wesley Chapel, Lutz, San Antonio, or New Tampa, affordability questions often come with an added layer of unfamiliarity — new lenders, new builders, new market norms. That’s where local guidance matters most.
I work with a network of preferred lenders who understand both conventional and new construction financing across Pasco and Hillsborough Counties, and who can walk buyers through FHA options, assistance programs, and builder incentive structures side by side, so the 401(k) conversation becomes one option among several rather than the default answer.
Sellers relocating and buying simultaneously face a related challenge: coordinating the sale of a current home with the purchase of a new one without ever needing to bridge the gap with retirement funds. This is a conversation worth having early, ideally before a home search even begins, so the numbers are clear from the start.
Whether you’re a first-time buyer or a move-up family, understanding your full range of options before deciding is the single best step you can take.
Explore Homes in Tampa Bay


Don’t Let Affordability Concerns Hold You Back — See What Your Down Payment Can Actually Buy in Tampa Bay
You don’t need to raid your retirement to find a home that fits your budget. Explore live listings across Tampa Bay’s most sought-after communities — many with builder incentives, rate buydowns, and low-down-payment financing options already built in.
•Family Communities in New Tampa
• First-Time Buyer Friendly Homes in Riverview
•New Construction in Wesley Chapel
• Valued Priced Homes in Odessa
Elena Esquen, MBA
Realtor® & Broker Associate
New Construction Specialist & Relocation Expert
Coldwell Banker Realty
📱 Phone: 813-822-4261
✉️ Email: Homes@EsquenTampaBay.com
🌐 Website: EsquenTampaBay.com
🏠 Resources: TampaHomesToday.com
🌴 Serving the Greater Tampa Bay Area
Frequently Asked Questions
1. Should I use my 401(k) to buy a home in Tampa Bay?
It’s possible, but national financial experts caution that early withdrawal penalties and lost investment growth can outweigh the short-term benefit. Speak with a financial advisor and a local REALTOR® before deciding.
2. What are the risks of borrowing from a 401(k) for a down payment?
Risks include early withdrawal penalties, taxes owed on the withdrawn amount, and the loss of future compounded investment growth — all according to national financial guidance from sources like Redfin and NerdWallet.
3. Are there down payment options besides using my 401(k)?
Yes. FHA loans allow down payments as low as 3.5% for qualified buyers, and many national and local down payment assistance programs can reduce upfront costs.
4. Does Tampa Bay have builder incentives that lower down payment needs?
Many new construction communities in Wesley Chapel, Land O’ Lakes, and Odessa offer builder incentives such as rate buydowns and closing cost credits that can reduce the cash needed at closing.
5. What is a CDD fee, and does it affect my down payment or closing costs?
A CDD (Community Development District) fee is a Florida-specific assessment used to fund community infrastructure. It’s typically a separate cost from your down payment but should be factored into your total monthly housing budget.
6. Is now a good time to buy in Tampa Bay if affordability is tight?
Affordability challenges exist nationally, but Tampa Bay continues to offer relative value for relocating buyers, especially when paired with the right financing strategy and local incentive knowledge.
7. How can a Tampa Bay REALTOR® help me avoid tapping my retirement savings?
A knowledgeable local REALTOR® can connect you with preferred lenders, identify builder incentives, and walk you through assistance programs — often uncovering financing paths buyers didn’t know existed.
Disclaimer
This article is intended for informational purposes only and should not be considered financial, legal, tax, or real estate advice. Market conditions, loan program availability, and financial regulations can change at any time. Data referenced from Empower, Redfin, Bankrate, and NerdWallet reflects national trends and may not reflect Tampa Bay–specific conditions. For personalized guidance regarding your real estate and financing goals in Tampa Bay, Wesley Chapel, Lutz, Odessa, San Antonio, or surrounding Florida communities, contact me directly.